Roof financing works in three steps: apply online or during your inspection and get a decision in minutes, choose a plan and a down payment once approved, then sign digitally and schedule the job, with the lender paying the roofer only after the work is done. The parts that trip people up are not the three steps, they are what happens when the application does not go exactly as planned: a cosigner, an approval for less than asked, or a promo deadline that is about to pass.
I am Aaron Scott, a licensed Michigan residential builder and the owner of Roofing Army. We are based in Oxford with offices in Rochester Hills, Ferndale, and Plymouth, and we never take a deposit, financed or paid outright. Financing and payment questions come up on 217 of the calls and texts we field in a typical stretch: 53 about the monthly payment, 35 about qualifying, 33 about whether a deposit is required, 10 about a card fee, and 8 about assistance programs. Our roof financing options guide covers the two plan shapes we offer and the basic deferred-interest trap to watch for; this guide goes further into the parts of the process that guide does not: cosigners, partial approvals, what to actually do when a promo is about to end, and what real assistance programs exist in Michigan.
How does the roof financing application process actually work?
It runs alongside the estimate, not after it, so a roof decision and a payment decision can happen in the same visit:
- Apply. Fill it out online on your own time, or let your inspector walk you through it during the in-home estimate. Most applications return a decision in a few minutes.
- Choose a plan and a down payment. Once approved, you decide how much to put down, if any, and which plan shape fits your budget.
- Sign and schedule. Loan documents are signed digitally. We schedule the roof, and the lender releases funds to us only after the job is complete and you have signed off.
Loan amounts run from $1,000 to $100,000, and applying may involve a credit check, though the impact on your score is typically minor and varies by profile. No legitimate roof financing program skips the credit check entirely, so treat any offer that claims otherwise the same way you would treat a bid that shows up on your door the week after a storm.
Can you add a cosigner to a roof financing application?
Many personal and home-improvement lenders allow a cosigner, someone who agrees to be equally responsible for the loan if the primary applicant's income or credit alone does not clear the lender's bar. A cosigner is not a character reference. Their name goes on the loan, missed payments show up on their credit report the same as the borrower's, and they are legally on the hook for the balance if you cannot pay. Whether a specific lender in our network allows a cosigner, and what documentation they need from that person, varies, so this is a direct question to ask during the application, not an assumption to make going in. If a cosigner is not an option for a given lender, that is exactly the situation the next section covers.
What happens if you are approved for less than you asked for?
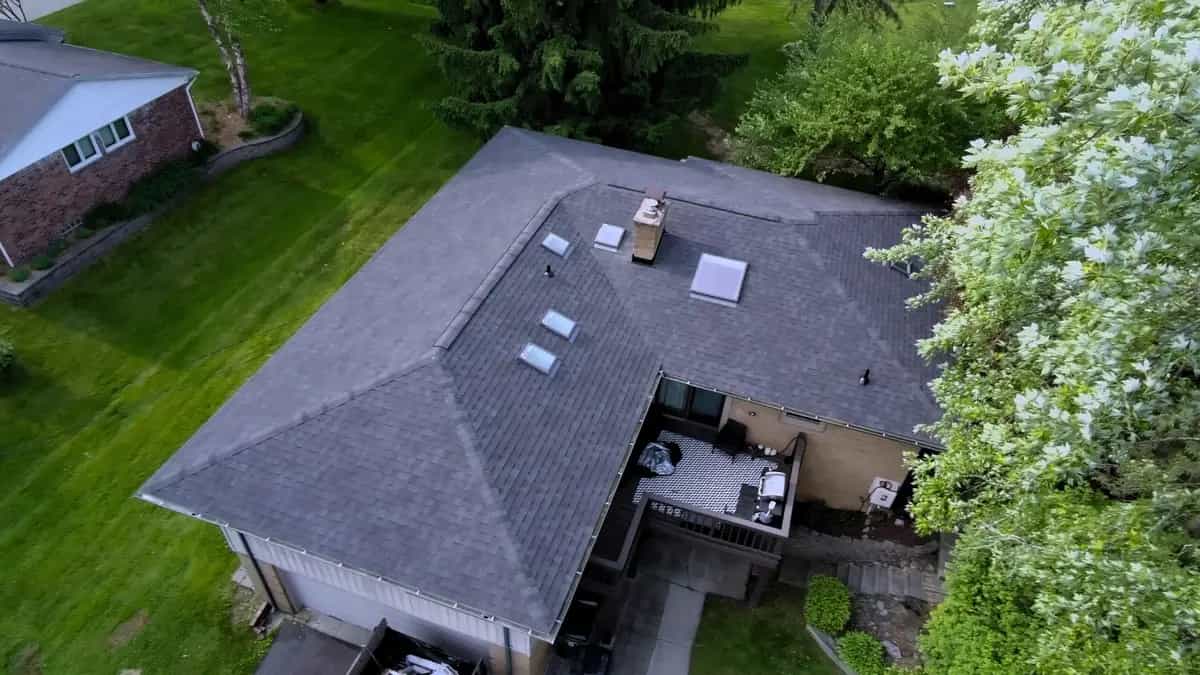
A partial approval is common and is not a rejection. Lenders set a limit based on income, existing debt, and credit profile, and that number does not always match the roof's price. Say a roof costs $25,796.00, the real price of the job we completed at 1765 Ledbury Drive in Bloomfield Township (3,760 sq ft), used here for real math, not as a quote on your own roof. If a lender approves $20,000 against that project, the $5,796.00 gap has to come from somewhere. In practice, homeowners cover it one of a few ways:
- A bigger down payment. Pay the gap in cash up front and finance the rest.
- A second lender. We work with a few different lenders rather than one captive finance company precisely because a profile one lender caps at $20,000, another may approve further on different terms.
- A different quote tier. We give every customer five quotes at different price points, so a homeowner short on approved financing can choose a good-better-best configuration that fits the number the lender actually gave, rather than walking away from the roof entirely.
- Reapply later. If your financial picture changes, lenders generally expect a waiting period before a new application improves the outcome, so this is the slowest option, not the first one to reach for.
What a partial approval is not is a bid to negotiate with the roof itself. Skipping ice and water shield or downgrading to a shorter workmanship warranty to shave the price to match a financing cap is how a homeowner ends up with a cheaper roof instead of a cheaper payment on the same roof. Compare the full line-item list in our Michigan roof replacement cost guide before you decide what to cut.
What actually happens when a 0% promotional period ends?
Our financing options guide explains the deferred-interest mechanism itself: on many 0% promotions, interest accrues in the background from day one and is only waived if the full balance is paid before the deadline. What that guide does not walk through is what to actually do as that deadline approaches:
- Check your real payoff balance before the deadline, not after. Your statement shows what is left to pay. Do this at least a month out, not the week the promo ends.
- If you cannot pay it off in time, call the lender before the deadline, not after. Ask directly whether the plan can be extended, refinanced into a longer term, or paid down with a lump sum to avoid the retroactive interest charge. Lenders would generally rather restructure a loan than have a customer miss the cutoff by surprise.
- A missed deferred-interest deadline is retroactive to day one, not just forward from the deadline. That is the detail that catches people off guard: the bill is not "interest from here forward," it is the full accrued interest for the entire promotional period, added all at once.
- A true 0% APR plan does not have this risk. If a balance remains after a true 0% term, interest starts accruing from that point forward, not backdated. Confirm in writing which type you have at the time you sign, not when the deadline is three weeks away.
Are there financial assistance programs for a new roof in Michigan?
A small number of calls we get, 8 of the 217 financing calls, ask about assistance programs, and the honest answer is that broad "free new roof" grants are rare. What actually exists in Michigan is narrower and income-qualified. State law, the Public Assistance Home Repair, Weatherization, and Shutoff Protection Act (MCL 400.1151 to 400.1165), defines "home repairs" to include roof repair or replacement when a home energy analysis identifies the roof as necessary work before weatherization measures can be installed, for low-income households, defined in the statute as incomes below 125% of the federal poverty line. The same law caps the department's authorized spending on a given home at $5,000.00 or 50% of the home's estimated market value, whichever is less, so this is help with a roof problem that is blocking an energy-efficiency upgrade, not a program that pays for a full roof replacement on its own. The Michigan Department of Health and Human Services administers the Weatherization Assistance Program, delivered locally through county Community Action agencies, which is the right place to start if you think you might qualify.
Outside that narrow program, we see homeowners search for government roof grants far more often than they find one. A home equity loan or line of credit through your own bank is a more realistic path for most homeowners who do not qualify for contractor or lender promotional terms, and it runs as a separate application from the roofing estimate.
Is there a fee to pay with a credit card?
This comes up on about 10 of our financing calls. The honest answer is that it depends on the processor and the lender, not on us: some payment processors add a small surcharge for credit card transactions that is separate from anything Roofing Army sets, and some financing plans are structured as a loan rather than a card charge in the first place, which avoids the question entirely. Ask directly whether a given payment method carries a fee before you choose one, the same way you would ask a doctor's office or a contractor billing by card anywhere else.
Do you need a deposit either way?
No. Financed or paid in full, we do not take a deposit on any job. The lender releases funds to us after the roof is complete and you have signed off on it, so your money, or the lender's money on your behalf, stays in your control until the work is actually done. If a roofer, financed through them or not, asks for a large sum before a shingle is delivered, get a second opinion before you sign anything.
Get a Real Application Started
Every roof has an exact price, and financing works best once you have it. We serve Southeast Michigan from offices in Oxford, Ferndale, Rochester Hills, and Plymouth, with five written quotes at different price points on every estimate. See current plan shapes on our financing page, run your own project's numbers in the roof financing calculator, or schedule a free inspection to get real numbers and a real application started.
Frequently Asked Questions
How does the roof financing application process work?
It runs alongside the estimate: apply online or during your in-home inspection, get a decision in a few minutes, choose a plan and a down payment once approved, then sign loan documents digitally. We schedule the job, and the lender pays us only after the roof is complete and you are satisfied, so financing does not change our no-deposit policy.
Can I add a cosigner to a roof financing application?
Many lenders allow it when a primary applicant's income or credit alone does not clear their approval bar, but it varies by lender, and a cosigner becomes equally responsible for the loan, including the effect on their own credit if a payment is missed. Ask the specific lender directly during the application rather than assuming it is available.
What happens if a lender approves me for less than I need?
A partial approval is common, not a rejection. Homeowners typically close the gap with a larger down payment, a second lender (we work with a few rather than one), a different quote tier since we give five at different price points, or by reapplying later if their financial picture changes. We do not recommend cutting ice and water shield, warranty length, or other scope to force the price down to match a financing cap.
What happens if I do not pay off a 0% plan before the promo ends?
On a deferred-interest promotion, missing the deadline means the lender can add back interest that accrued from day one, not just interest going forward. Check your real payoff balance at least a month before the deadline, and if you cannot pay it off in time, call the lender before the deadline to ask about extending or refinancing. A true 0% APR plan does not carry this retroactive risk.
Are there government programs that help pay for a roof in Michigan?
A narrow one. Michigan's Weatherization Assistance Program can fund roof repair or replacement when a home energy analysis finds the roof is blocking weatherization work, for households under 125% of the federal poverty line, administered locally through county Community Action agencies. State law caps the authorized amount at $5,000 or 50% of the home's market value, whichever is less, so it is help with a qualifying roof problem, not a program that covers a full replacement on its own.