Roofing Army's financing comes in two basic shapes: promotional no-interest plans with $0 down, and longer, low-interest plans that spread a bigger project into a lower monthly payment. Loan amounts run from $1,000 to $100,000, most applications get a decision in minutes, and we never require a deposit either way, financed or not. Here is what each option actually means for your wallet, and what to ask before you sign.
I am Aaron Scott, a licensed Michigan residential builder and the owner of Roofing Army. We are based in Oxford with offices in Rochester Hills, Ferndale, and Plymouth, and a project manager is on site for every job we run, financed or paid in full. Financing questions come up on 217 of the calls and texts we field in a typical stretch, more than almost any other topic besides the price itself, so this guide covers what homeowners actually ask us.
What roof financing options does Roofing Army actually offer?
We partner with a few different lenders rather than one captive finance company, so there are plans for most credit profiles and budgets. The options fall into two shapes:
- No-interest plans. A promotional term with $0 down and no interest charged, for homeowners who would rather pay nothing extra and can handle a higher monthly payment over a shorter term.
- Long-term, low-interest plans. A longer term that lowers the monthly payment on a larger project, with no prepayment penalty if you want to pay it off faster later.
Exact rates and terms depend on the lender and your approval, and they are not something we publish as fixed numbers because they change with the lending market. Our financing page has the current plans, and our roof financing calculator lets you model any cost, rate, and term yourself. For reference, two plan shapes we see often are 0% for 60 months and 8.99% for 120 months. The math below uses those as examples, not a quote.
How does the financing application actually work?
It is a three step process, and it runs alongside the normal estimate process rather than after it:
- Apply. Apply online whenever you want, or fill it out during your in-home inspection. Most applications get a decision in a few minutes.
- Choose a plan. Once approved, decide how much to put down, if any, and pick the loan option that fits your budget.
- Sign and schedule. Loan documents are signed digitally, we schedule the roof, and the lender releases funds to us after the work is complete, not before.
That last point matters: financing does not change our no-deposit policy. Whether you pay cash or finance, you are not paying us anything until the job is done and you are satisfied with it.
Do you need good credit to finance a roof in Michigan?
You do not need perfect credit, but you do need to pass a credit check, approval is not automatic. Applying may involve a credit check, and the impact on your score is typically minor and varies by individual profile. About a third of the financing calls we get are from homeowners asking whether they will qualify. The honest answer is that it depends on the lender and your profile, which is exactly why we work with several lenders instead of one: a profile that one lender turns down, another may approve on different terms. If you see an ad promising a new roof with no credit check at all, treat it with the same skepticism you would a bid that showed up on your door the week after a storm. We have never seen a legitimate roof financing program that skips the credit check entirely.
Is 0% roof financing actually free?
If you pay off the balance inside the promotional term, yes, you pay exactly the project cost and nothing more. The catch is specific to a type of promotion called deferred interest, which is common in retail and home improvement financing generally: interest accrues in the background from day one, and it is only waived if the full balance is paid before the promo period ends. Miss the deadline, even by a small remaining balance, and the lender can add the accrued interest to your bill retroactively. A true 0% APR plan works differently: if a balance is left after the term, interest starts from that point forward rather than being backdated. Before you sign any 0% offer, from us or anyone else, ask the lender directly which type you are getting and get the promo end date in writing. It is a five minute question that can be worth thousands of dollars.
What does a roof actually cost per month, financed?
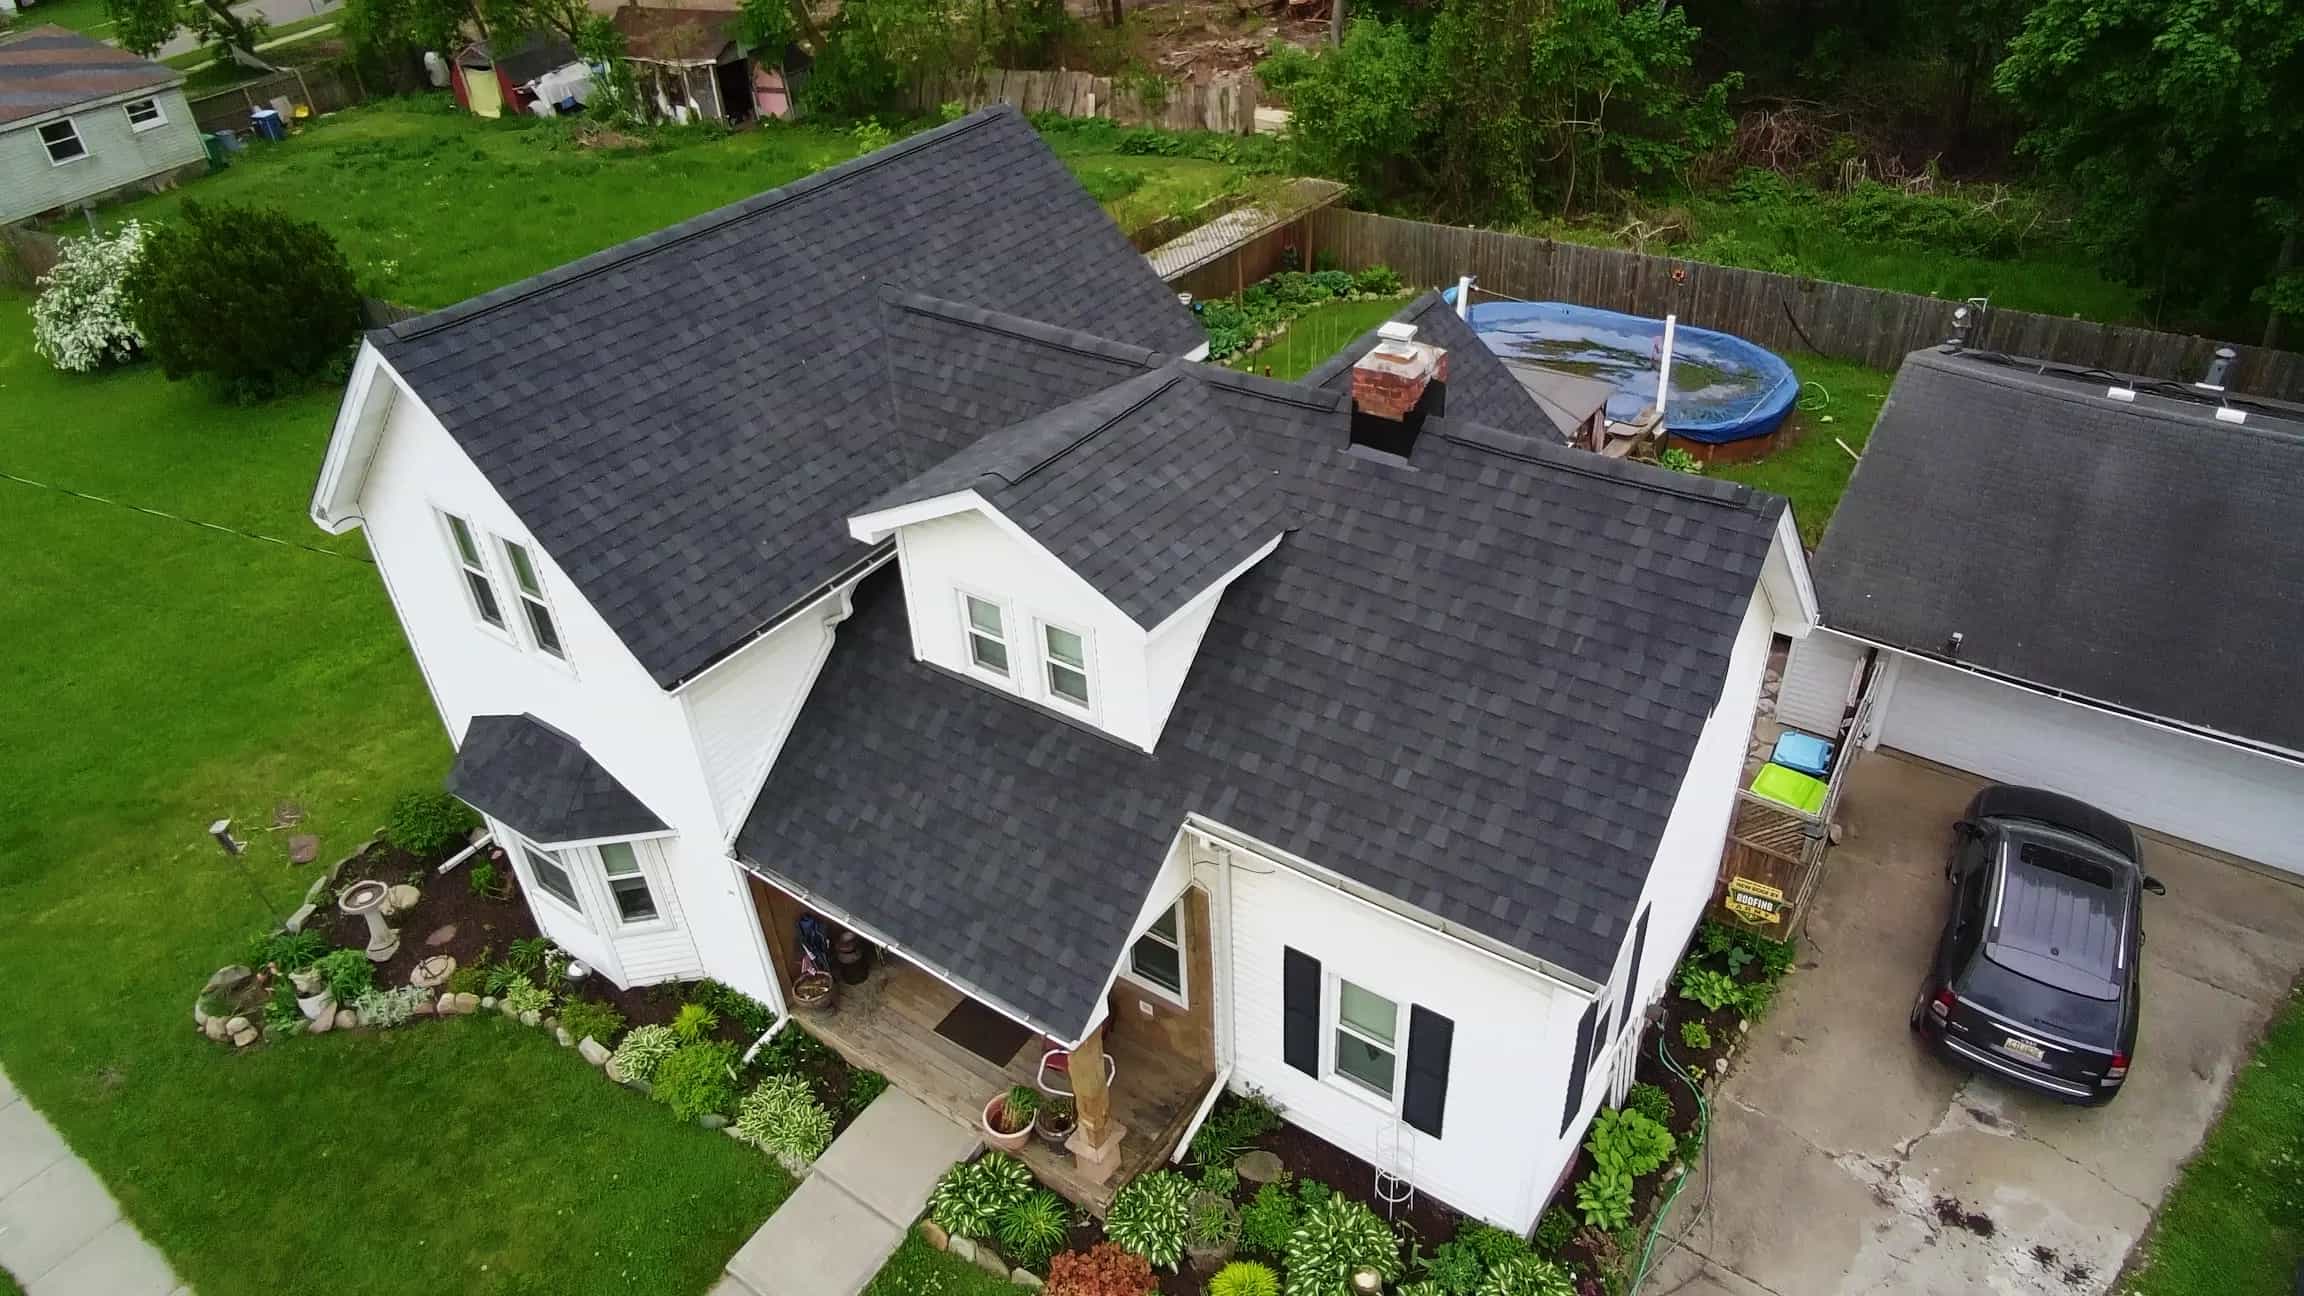
Real numbers make this easier to picture than a hypothetical. We replaced a 2,323 sq ft roof at 51782 Flyer Drive near Macomb Township for $15,693.00. Here is what that project looks like under each plan shape:
| Plan | Monthly payment | Total paid | Interest | Cost per day |
|---|---|---|---|---|
| 0% for 60 months | $261.55 | $15,693.00 | $0 | $8.60 |
| 8.99% for 120 months | $198.71 | $23,844.88 | $8,151.88 | $6.53 |
Same roof, same lender category, two very different outcomes. The shorter 0% plan costs $63 more a month but saves $8,151.88 over the life of the loan. The longer plan drops the monthly payment by about a quarter, which matters if cash flow is the real constraint, but you are paying for that flexibility. Run your own project's number through our financing calculator, which uses the same math against your actual roof cost.
Can you finance only part of the job, or add costs found later?
Yes to both. Once approved, you choose how much to put down and finance the remaining balance on whichever plan you pick, you are not required to finance the entire project. And if our crew finds something during tear off that was not in the original scope, rotted decking is the most common one, an approved change order can typically be added to the existing financing so you are not juggling two separate bills. That said, decking replacement is priced per sheet and disclosed in writing before the job starts whenever we can see it coming, so surprises are the exception, not the plan.
What if a storm caused the damage, should you finance or claim it?
If an insurance claim is covering some or all of the job, finance the gap, not the whole roof. Work out what your policy actually pays first using our insurance claim calculator, then finance your deductible and any upgrades the insurer will not cover. Filing a claim is rarer than people expect, only about 3% of the roofs we quote end up filed as insurance claims, so for most homeowners financing is the more direct path. If you are still deciding whether the roof needs to be replaced at all, our guide on repair versus replacement covers that decision first.
Are there other ways to pay for a roof besides contractor financing?
Some homeowners use a home equity loan or home equity line of credit through their own bank instead, which can carry different rates depending on your equity and credit, and the application runs separately from the roofing estimate. Others simply pay cash, which is still the cheapest option whenever it is available since there is no interest at all. We do not push one path over another, our job is to give you an accurate project cost so you can compare it against whatever payment method actually works for your situation.
Do you need a deposit to finance a roof?
No. We do not take deposits on any job, financed or paid outright. The lender releases funds to us after the roof is complete and you have signed off on it, which means your money, or the lender's money, stays in your control until the work is actually done. If a roofer asks you for a large upfront deposit before a shingle is delivered, financed through them or not, that is worth a second opinion before you sign anything.
Get Your Real Number
Ranges and example plans are useful, but your roof has an exact price and an exact payment. We serve Southeast Michigan from offices in Oxford, Ferndale, and Rochester Hills, including Berkley and the surrounding communities, and we give every customer five quotes at different price points so you can pick the roof and the payment that actually fits. See current plans on our financing page, estimate a payment with the financing calculator, or schedule a free inspection to get real numbers for your own roof.
Frequently Asked Questions
What roof financing options does Roofing Army offer?
Two basic shapes: promotional no-interest plans with $0 down, and longer, low-interest plans that lower the monthly payment on a larger project. We work with a few different lenders, so plans vary by credit profile. Loan amounts run from $1,000 to $100,000, and there is no prepayment penalty on either shape.
Does financing a roof require a credit check?
Yes. Applying may involve a credit check, though the impact on your score is typically minor and varies by individual profile. We have never seen a legitimate roof financing program that skips the credit check entirely, so be cautious of any offer that claims otherwise.
Is 0% roof financing really interest free?
It can be, if you pay off the balance inside the promotional period. Some 0% promotions are deferred interest, meaning unpaid interest accrues in the background and gets added to your bill if you miss the payoff deadline. Always ask the lender directly whether a 0% offer is deferred interest or true 0% APR, and get the promo end date in writing.
Do you need a deposit if you finance a roof?
No. We do not require deposits on any job, financed or paid outright. The lender releases funds to us only after the roof is complete and you are satisfied, so your payment stays tied to the finished work either way.
Can I finance only part of a roof replacement?
Yes. Once approved, you decide how much to put down and finance the remaining balance on the plan you choose. If an approved change order comes up during the job, such as rotted decking found at tear off, it can typically be added to your existing financing rather than becoming a separate bill.