Roof Insurance Claim Calculator
Estimate the replacement cost value (RCV) of a storm claim across the trades that were hit.
Estimated claim value (RCV)
$13,200
The roof line uses the middle of our published per-square-foot range. Gutter, siding and window lines are rough allowances so the total is in the right neighborhood; those trades are handled by our referral partners, and the adjuster's estimate will price them line by line. On an RCV policy the insurer holds back depreciation until the work is done.
A roof insurance claim has three numbers that matter: the replacement cost value (RCV) of everything the storm damaged, your deductible, and what is left for the insurer to pay. The calculator above estimates the roof portion from your footprint and pitch using our real published job prices, adds allowances for gutters, siding, and windows if they were hit, subtracts your deductible, and shows the insurer's share. I am Aaron Scott, a licensed Michigan residential builder and the owner of Roofing Army. This guide explains the estimate and how it compares to the adjuster's worksheet.
What does the roof insurance claim calculator estimate?
Enter your roof footprint, pitch, insured value, and deductible, then check off which trades the storm damaged: the roof, gutters, siding, and how many windows. The tool returns an estimated RCV for the whole claim, your deductible in dollars, and the amount the insurer should pay under a replacement cost policy.
RCV is the number an adjuster builds first. It is what it would cost today to put back what the storm took, before any depreciation. If your policy pays replacement cost, RCV minus your deductible is what you should ultimately collect, usually as an initial check plus recoverable depreciation released after the work is done. If your policy pays actual cash value, the insurer keeps the depreciation. Our guide to how Michigan homeowners insurance covers a roof explains both.
How does the calculator get its numbers?
The roof line is the one we can price with confidence, because it comes from our own invoices. We publish every project's price and roof area in our job gallery. Dividing price by area, half of our published asphalt jobs landed between $5.99 and $7.07 per square foot of roof. The calculator multiplies your footprint by the pitch factor to get roof area, then applies that band.
The gutter, siding, and window lines are different. Roofing Army does not install gutters or siding; those are handled by our referral partners, Ackerman Seamless Gutters and The Exterior Painters, while we coordinate the roof. The calculator carries placeholder allowances for those trades so the claim total is not missing obvious line items, but the real figures come from the partners' own estimates and the adjuster's software. Treat them as reminders to include the trade, not as prices.
Deductible math follows your policy: a flat dollar amount, or a percentage of the insured value for wind and hail. The hail deductible calculator isolates that piece if you want to compare deductible options.
Worked example: a hail-totaled roof in Rochester
Our Longford Drive replacement in Rochester was a 3,030 square foot roof that cost $18,440.16, which is $6.09 per square foot. Enter a footprint and pitch that produce about 3,000 square feet of roof area and the calculator's roof RCV lands between roughly $18,000 and $21,400. The real invoice sits at the low end of that band, because it was a straightforward roof with good decking.
On a home insured for $350,000 with a 1% wind and hail deductible, your share is $3,500. Against the actual $18,440.16 price, the insurer pays $14,940.16, about 81% of the roof. At 2% the deductible is $7,000 and the insurer pays $11,440.16. Add dented gutters and two damaged windows and the RCV climbs while the deductible stays fixed, so the insurer's share of the total claim rises. That is why it matters to get every damaged trade on the claim the first time.
Worked example: a small roof and a percentage deductible
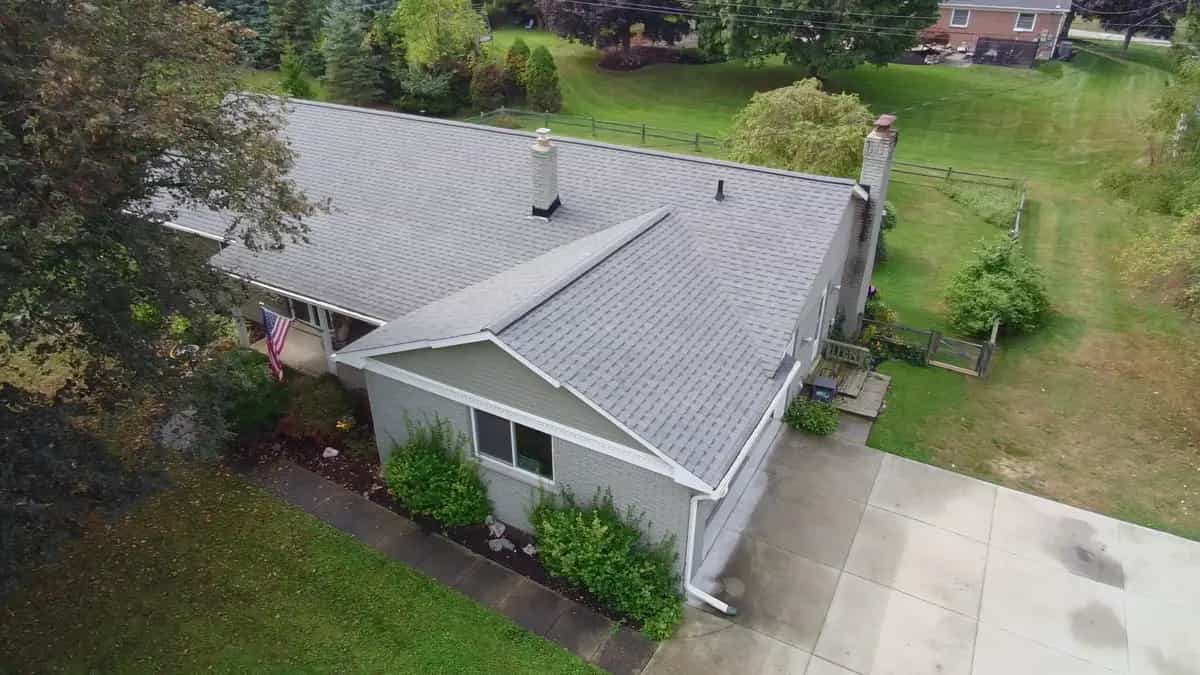
Our East Brockton Avenue project in Madison Heights is the most affordable roof we have published: 1,048 square feet at $6,412.15. On a $250,000 policy with a 2% deductible ($5,000), the insurer pays $1,412.15 on the roof alone. If the storm also took the gutters, that changes the picture, because the deductible only comes off once. But a roof-only claim on that house barely clears the deductible and would sit on your claim history, which the Michigan Department of Insurance and Financial Services notes insurers use when setting your premium.
How does the calculator compare to the adjuster's estimate?
Adjusters price claims with estimating software that lists every component: tear-off, underlayment, ice and water shield, drip edge, shingles, ridge cap, vents, flashing, and disposal, each with a quantity and unit price. Our calculator compresses that into a per-square-foot band drawn from finished jobs, which is why the two numbers should be close but will not match line for line. The places they diverge most:
- Waste and complexity. Adjuster software adds a waste percentage for hips and valleys. Cut-up roofs get more. The calculator's band already includes typical waste but not the extremes.
- Layers and decking. A second layer to tear off or rotted decking discovered on tear-off gets added by supplement after the fact. Our Michigan claim guide covers how supplements work.
- Code items. Ice and water shield to the Michigan Residential Code minimum is typically included. The 6 feet we install as standard is not, and the insurer will not pay for the extra.
- Overhead and profit. Some carriers add it when three or more trades are involved, which is another reason gutters and siding belong on the same claim.
What can the calculator not see?
Whether the damage is covered at all, which is a question of cause and policy language, not math. How old the roof is and whether your policy has moved it to ACV or a roof payment schedule. Whether the adjuster finds qualifying damage on every slope. And what the roof looks like once the shingles come off. None of that is in a footprint number, and all of it moves the check. It is why a project manager from our crew meets the adjuster on the roof: the estimate on paper should reflect the damage on the deck.
What should you do next?
Use the calculator above to get a working RCV, then document the damage and get an inspection before you file. We handle storm claims across Southeast Michigan from offices in Oxford, Ferndale, Rochester Hills, and Plymouth, including Rochester, Troy, and Plymouth. See how our storm damage service works, and if the claim comes up short of a full replacement, our financing options can bridge the difference.
Frequently Asked Questions
What is replacement cost value (RCV) on a roof insurance claim?
RCV is the full cost, at today's prices, to replace the damaged roof and any other damaged components with materials of like kind and quality. On a replacement cost policy you receive RCV minus your deductible, usually paid as an initial actual cash value check followed by recoverable depreciation once the work is complete and invoiced.
Does the deductible apply to each trade on a storm claim?
No. One deductible applies to the whole claim from a single event. If hail damaged your roof, gutters, and siding, the deductible comes off the combined total once, which is why including every damaged trade on the same claim raises the share the insurer pays.
Who handles the gutters and siding on my claim?
Roofing Army coordinates and installs the roof. Gutters and gutter guards are handled by our referral partner Ackerman Seamless Gutters, and siding by The Exterior Painters. They provide their own estimates for the claim, and we coordinate scheduling so the exterior work comes together in the right order.
Why is the adjuster's estimate lower than the calculator?
Common reasons: the policy pays actual cash value and depreciation was removed, the adjuster approved a repair rather than a replacement, a second shingle layer or decking was not visible during inspection, or items like drip edge and vents were omitted. You can request a re-inspection with your contractor present and submit a supplement for missed items.
How long does a Michigan insurer have to pay a roof claim?
Under MCL 500.2006, once the insurer has a complete proof of loss, it has 60 days to pay before the claim begins accruing 12% annual interest. Disputes over the amount can go to appraisal under the policy's appraisal clause, or you can file a complaint with the Michigan Department of Insurance and Financial Services.