Hail and Wind Deductible Calculator
What you pay out of pocket before insurance covers a storm-damaged roof.
Percentage deductibles are figured on the dwelling coverage amount, not the claim.
Your out-of-pocket deductible
$7,000
A claim that pays $0 still goes on your claim history. When the deductible is close to the repair cost, a paid repair is usually the better move. We inspect for free and tell you which side of that line you are on.
A percentage wind and hail deductible is calculated on your home's insured value, not on the size of the roof claim. On a home insured for $350,000, a 2% deductible is $7,000 out of pocket before the insurer pays anything, and on a $250,000 policy a 2% deductible can swallow most of a small repair claim. The calculator above turns your policy's deductible into real dollars, shows what your insurer would pay on a given repair cost, and flags when a claim is not worth filing. I am Aaron Scott, a licensed Michigan residential builder and the owner of Roofing Army, and our crews meet adjusters on Southeast Michigan roofs every storm season. This guide explains what the tool is doing and what it cannot see.
What does the hail deductible calculator estimate?
It answers the three questions homeowners ask us in the driveway after a hailstorm: what is my deductible in dollars, what would insurance actually cover, and what percentage of the bill lands on me. You enter your home's insured value (the Coverage A or dwelling limit on your declarations page), pick the deductible your policy uses, and enter an estimated repair or replacement cost. The tool returns your out-of-pocket deductible, the amount the insurer would pay, and the percent of the job that is covered.
The deductible options mirror what we see on Michigan declarations pages: a flat $1,000, $1,500, or $2,500, or a percentage deductible of 1%, 2%, or 5% of the insured value. If your policy has a different figure, use the closest option and adjust in your head; the math is linear.
How does the calculator get its numbers?
The math is deliberately simple, because the policy math is simple. A percentage deductible is the percentage multiplied by the dwelling limit. A flat deductible is the flat amount. The insurer's share is the covered repair cost minus the deductible, and it never goes below zero. Percent covered is the insurer's share divided by the repair cost.
What the tool does not do is guess at depreciation. If your policy pays actual cash value on the roof rather than replacement cost, the insurer's check will be smaller than the calculator shows, sometimes by half on an older roof. Our guide to what homeowners insurance covers on a Michigan roof walks through the ACV versus RCV difference in detail.
Why do Michigan policies use percentage wind and hail deductibles?
The Michigan Department of Insurance and Financial Services (DIFS) is the state's authority on homeowners insurance, and its consumer guidance explains the economics plainly. DIFS notes that when large numbers of claims are filed after bad weather such as heavy winds and tornadoes, companies may pay out more than they anticipated, and that this increased frequency of claims is one reason premiums rise. DIFS also tells consumers that increasing your deductible lowers your premium, and its homeowners insurance guide suggests considering the largest deductible your budget can handle to reduce premium cost.
A separate wind and hail deductible calculated as a percentage of the dwelling limit is how carriers apply that trade-off to the specific weather losses that drive roof claims. DIFS does not publish a count of how many Michigan policies now carry one, but on the declarations pages our customers hand us, percentage deductibles of 1% and 2% have become common. DIFS advises reviewing the declarations page of your policy so you understand what you have, and that advice is the whole point of the calculator above: know the number before the storm, not after.
What does a percentage deductible look like on a real Michigan roof?
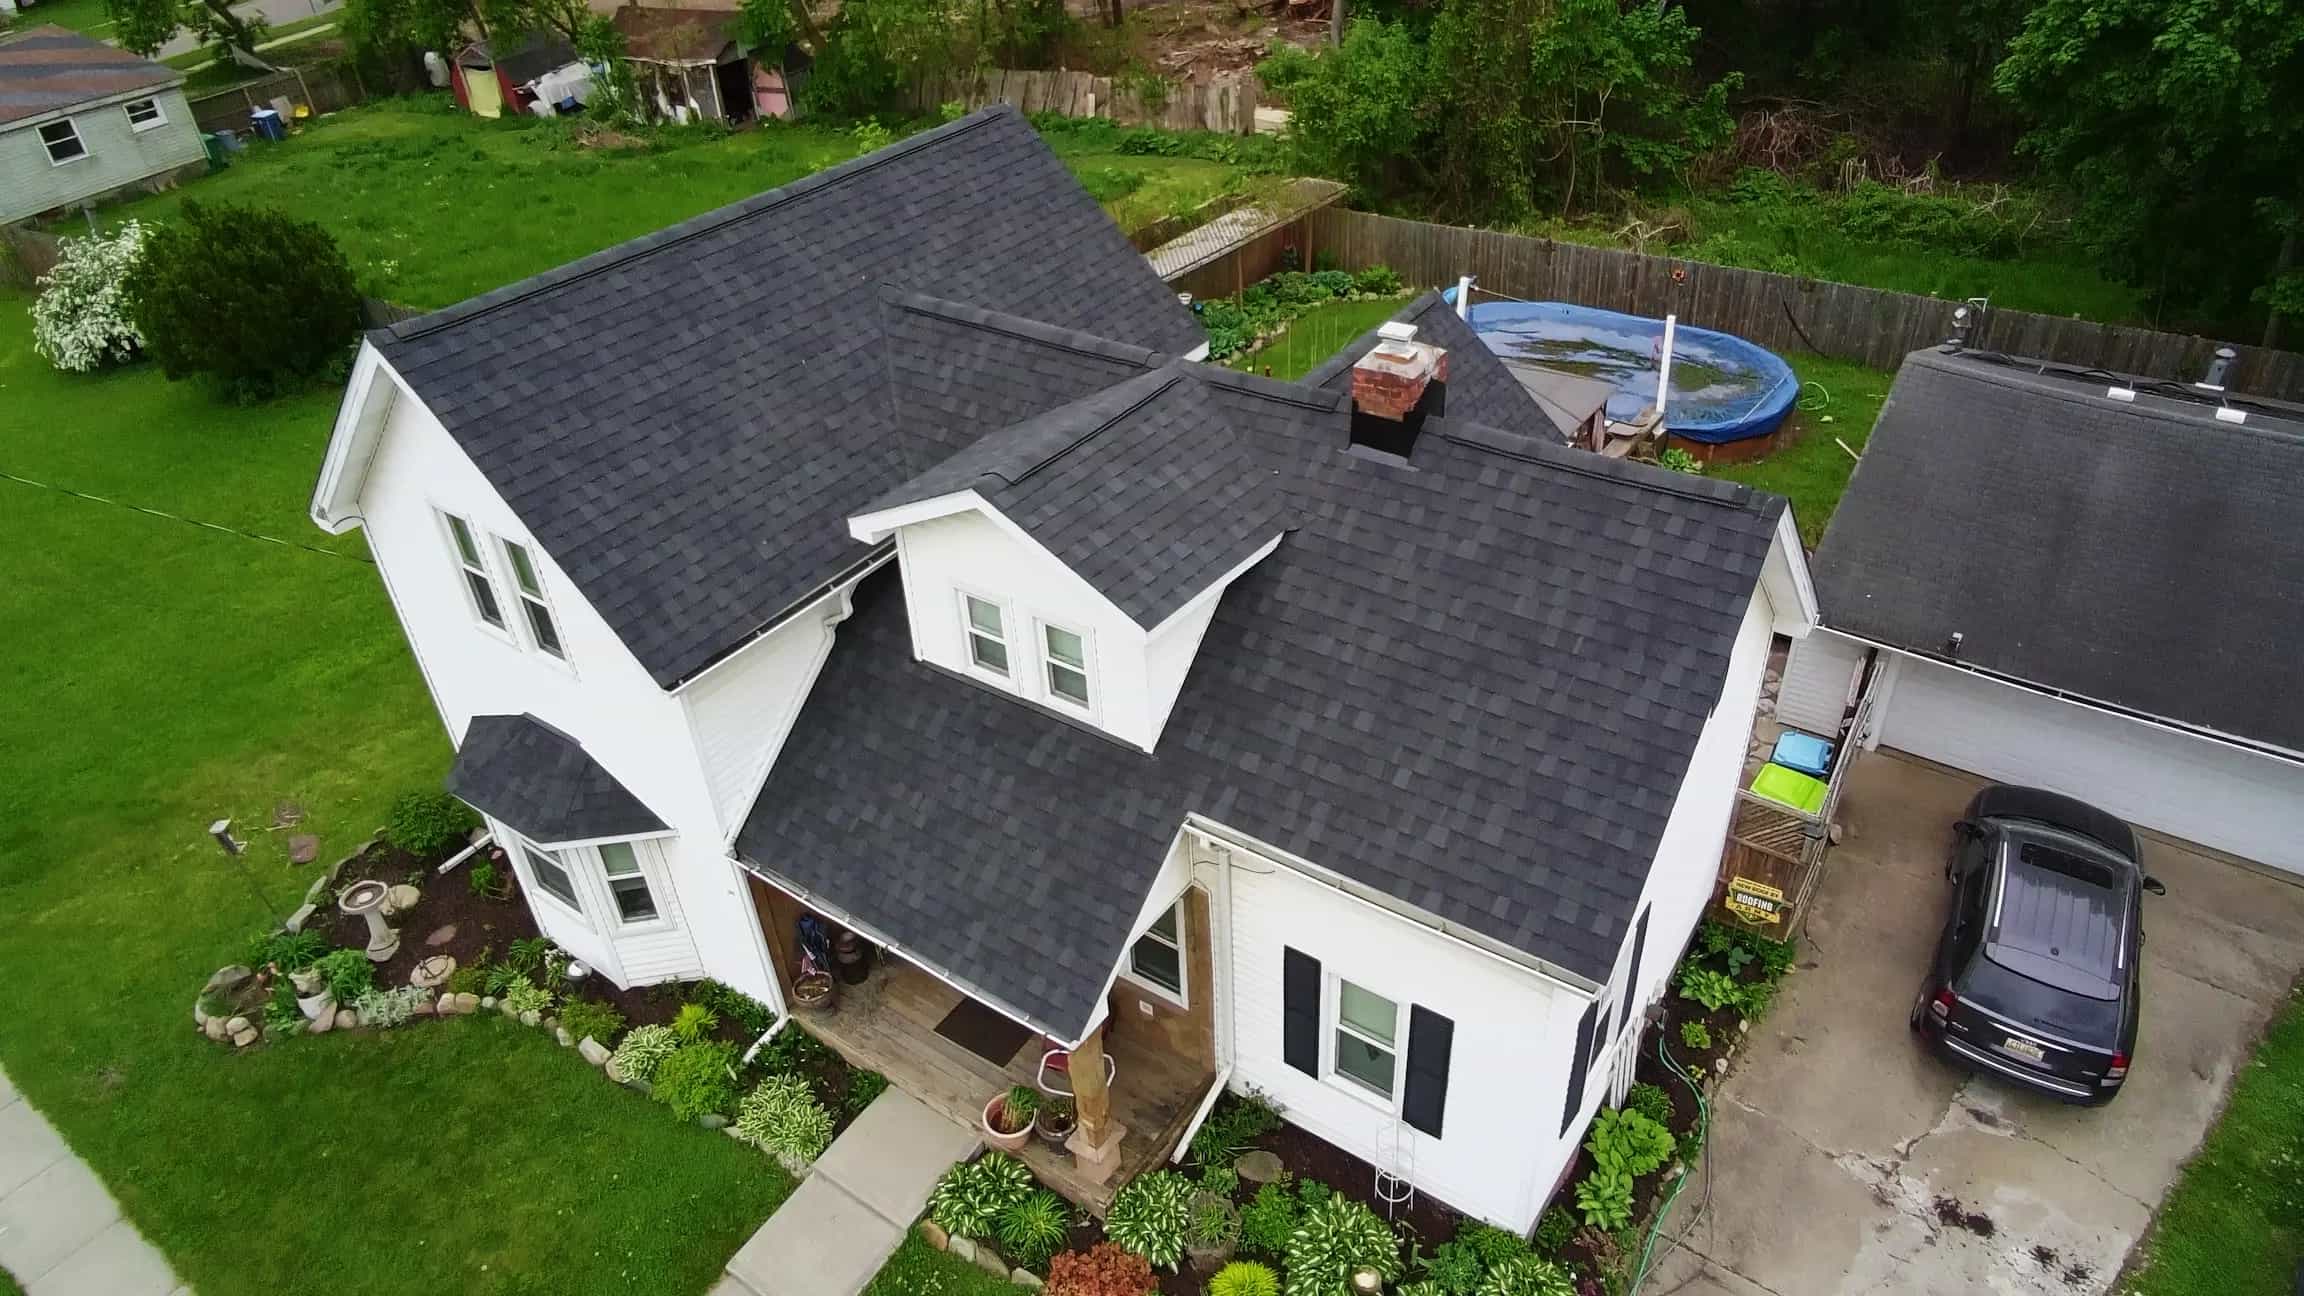
We publish the price of every project in our job gallery, so we can use real roofs instead of hypotheticals. Take our Rochester replacement on Longford Drive, a 3,030 square foot roof that cost $18,440.16. Here is what the calculator shows for that job on a home insured for $350,000:
| Deductible | Your share | Insurer pays | Percent covered |
|---|---|---|---|
| $1,000 flat | $1,000 | $17,440 | 94.6% |
| $2,500 flat | $2,500 | $15,940 | 86.4% |
| 1% of $350,000 | $3,500 | $14,940 | 81.0% |
| 2% of $350,000 | $7,000 | $11,440 | 62.0% |
| 5% of $350,000 | $17,500 | $940 | 5.1% |
The 5% row is the one that surprises people. On a full replacement of a mid-sized roof, a 5% deductible leaves the insurer paying almost nothing. If your policy carries one, you are effectively self-insuring the roof and should shop that deductible with your agent.
Now a smaller roof. Our Madison Heights replacement on East Brockton Avenue was a 1,048 square foot roof at $6,412.15. On a home insured for $250,000, a 2% deductible is $5,000, which leaves the insurer paying $1,412, about 22% of the job. At 5% the deductible is $12,500 and the insurer pays nothing at all. Filing a claim to collect $1,412 would put a claim on your record for very little return, which brings up the next question.
When is a hail claim not worth filing?
DIFS is clear that your claim history, meaning both the type and number of claims you have filed, is used by insurers to determine what to charge for coverage. DIFS also lists claim-free discounts among the common premium discounts, which you can lose by filing. So a claim has a cost even when it is approved. Our rule of thumb from years of storm work:
- Repair cost at or below the deductible: do not file. There is nothing to collect and you still take the claim on your record.
- Insurer's share is small relative to the deductible: get a real repair quote first. A wind-lifted slope that a roof repair can fix for a few hundred dollars is rarely worth a claim on a $2,500 or higher deductible.
- Insurer's share is most of a full replacement: file it. A hail-totaled roof is exactly what the coverage exists for.
- Older roof on an ACV policy: run the numbers with depreciation before deciding. The calculator's insurer share is the ceiling, not the floor.
When you do file, our step-by-step Michigan roof claim guide covers documentation, proof of loss deadlines, and what to do if the adjuster's number is low.
What can the calculator not see?
A few things only an inspection and your policy language can settle:
- Whether the damage is actually covered. Hail bruising and wind creasing are sudden events. Granule loss from age is not. An adjuster decides which one your roof has, and we make sure a project manager is on the roof with them so nothing is missed.
- Depreciation and roof schedules. Many carriers now pay ACV on roofs past a certain age, or use a roof payment schedule that steps coverage down each year.
- Other trades. Hail that dents a roof usually dents gutters, and sometimes siding and window wraps. Those go on the same claim but not through us; our referral partners handle gutters and siding while we coordinate the roof.
- Code upgrades and ventilation. Insurance pays to put back what was there. It does not pay for the ventilation corrections or the 6 feet of ice and water shield we install as standard, so a replacement done right may cost more than the claim.
What should you do after a hailstorm in Southeast Michigan?
Pull your declarations page and run the calculator above so you know your number. Then get an honest inspection before you call the insurer. We inspect storm damage at no charge across Oakland, Macomb, and Wayne counties, including Rochester Hills, Shelby Township, and Troy, and we will tell you plainly if the damage is below your deductible. Learn how our storm damage process works, or see what the whole repair might cost with our hail damage repair cost calculator.
Frequently Asked Questions
How is a percentage wind and hail deductible calculated in Michigan?
It is a percentage of your dwelling coverage limit (Coverage A), not a percentage of the claim. A 2% deductible on a home insured for $350,000 is $7,000, regardless of whether the roof claim is $8,000 or $28,000. Check your declarations page; the wind and hail deductible is usually listed separately from the all-perils deductible.
Does filing a hail claim raise my homeowners insurance premium?
It can. The Michigan Department of Insurance and Financial Services states that your claim history, both the type and number of claims filed, is used by insurers to determine what to charge for coverage, and many carriers offer claim-free discounts that a filed claim can remove. That is why a claim that only collects a few hundred dollars over the deductible is often not worth filing.
Can a roofing contractor waive or cover my deductible?
No. Your deductible is your legal share of the loss. Michigan regulators flag offers to cover or waive a deductible as a warning sign of contractor fraud, because it usually means the claim is being inflated or the roof is being shorted. A legitimate contractor will never make it disappear.
Why does the calculator show the insurer paying more than my check?
The calculator assumes replacement cost coverage and no depreciation. If your policy pays actual cash value on the roof, or uses a roof payment schedule, the insurer deducts depreciation for the roof's age and the check is smaller. Recoverable depreciation on an RCV policy is usually released after the work is completed and invoiced.
Is hail damage worth claiming if only one slope is damaged?
Often not, if you carry a percentage deductible. A single-slope repair may cost less than a 1% or 2% deductible on a typical Southeast Michigan home. Get a written repair quote first, compare it to your deductible with the calculator, and file only if the insurer's share is meaningful.